If you are financing a modular home, your lender will likely ask for a mortgage survey before closing. This is not the same as a full boundary survey. It is not paperwork you can skip and add later either. It shows where the home sits, or will sit, on the lot. Lenders use it to check that the property matches the loan application.
Modular homes bring their own timing questions to this process. A home that is already built and sitting on a foundation is easy to survey. A modular home is often still being planned or placed when the survey talk starts. That timing gap is why mortgage survey planning matters before you get deep into financing.
Why Modular Home Financing Can Trigger Survey Questions
Modular homes qualify for regular mortgage financing in most cases. But the loan process often runs into construction and foundation details that a normal home purchase does not involve. Lenders want proof that the home will sit where the plans say it will, on a lot that can support that spot.
This is where mortgage survey questions can pop up earlier than a buyer expects. If the home has not been set yet, the lender may still want to see the lot’s boundaries, current improvements, and the planned spot for the home. If the home is already set, the survey shifts toward showing what is actually there now.
Either way, the survey gives the lender a clear picture of the property tied to the loan. Without it, no one can confirm that the home sits where the paperwork claims it does.
What a Mortgage Survey Should Document Before Loan Review
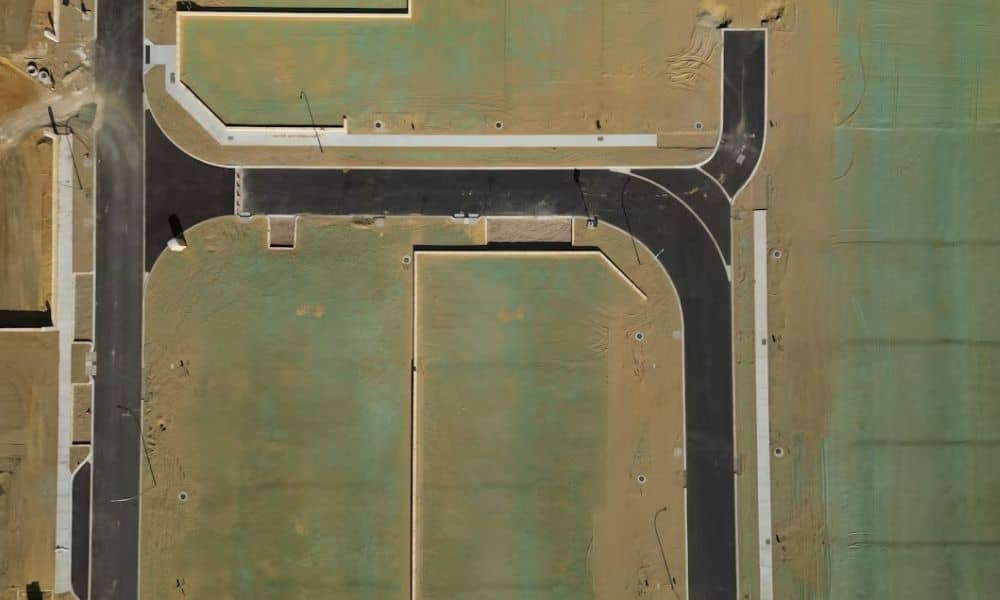
A mortgage survey for a modular home purchase or refinance usually shows the property boundaries, any existing structures, and where the modular home sits in relation to those boundaries. It often shows setbacks, driveways, and other visible improvements on the lot too.
This matters because the lender is reviewing the property as collateral for the loan. They need to see that the home fits inside the boundaries, meets basic setback rules, and does not sit on top of an easement or another structure. A survey that skips the home’s actual or planned spot does not give the lender what they need.
Owners should ask their surveyor what level of detail the lender wants before the field work starts. Some lenders ask for more than others. Confirming this early can save a second site visit down the road.
Coordinating the Survey Before Modular Home Placement
Setting up the mortgage survey before the modular home arrives can help avoid delays later. A surveyor can mark the lot’s boundaries, flag the planned spot for the home, and point out anything that could get in the way. This might be an easement, a setback line, or a buried utility line.
This step helps owners who have not locked in every detail of the site plan yet. If the home’s exact spot is still up in the air, a surveyor working from the real boundaries can confirm that the planned spot will actually work before the home shows up on a delivery truck.
Getting this done early also gives the lender something solid to review well before closing day, instead of a rushed document at the last minute.
When Site Changes Require Updated Survey Information
Changes made after the first survey can call for updated survey information before the loan can move forward. This includes moving the planned home spot, adding a driveway or a shed, or finding out during construction that the first plan will not work.
Lenders generally want the survey to match the property as it will actually look at closing, not just the original plan. If something changes after the first site visit, owners should ask their surveyor if an update or a new visit is needed. Do not assume the old survey still works.
This is one of the most common reasons a mortgage survey timeline shifts. Catching a change early is much easier than having it show up during the lender’s final review.
Planning a Mortgage Survey for Eastern Carolina Properties
Eastern Carolina has a mix of older neighborhoods and newer growth, which means modular home lots vary a lot from place to place. Some are small in-town lots. Others are larger properties still being divided up for new homes. Wilmington’s growth in recent years has added more of these projects to areas that were once open land.
That mix means survey needs can look different from one lot to the next. A small in-town lot may leave little room to adjust if a setback or easement gets in the way. A bigger lot often gives more room to work with. Owners planning modular home financing in this area should check survey needs early with both their surveyor and their lender, since the rules can change based on the property, the project, and the lender itself.
Frequently Asked Questions
Can a mortgage survey be completed before a modular home is set?
Yes. In many cases, a mortgage survey can start before the home is set, since it can show the lot’s boundaries and the planned spot for the home. Some lenders still want a follow-up survey once the home is in place, so check with the lender directly.
Does the lender decide what survey information is required?
Yes. Lenders usually set their own rules for what a mortgage survey needs to show, and these rules can differ from one lender to the next. It is best to confirm exact requirements with the lender before the survey gets scheduled.
Should the survey show the planned or completed modular home location?
This depends on where the project stands. If the home has not been placed yet, the survey may show the planned spot. Once the home is set, an updated survey showing the finished spot is often needed for final loan review.